Correlation Dynamics in Multi-Sport Outcome Modeling: Strategies for Tennis and Football Portfolio Integration
Written by Clara Werner · Jul 16, 2026
Correlation Dynamics in Multi-Sport Outcome Modeling: Strategies for Tennis and Football Portfolio Integration
Outcome probabilities in tennis and football display measurable correlation structures that analysts track through historical datasets spanning multiple seasons. These patterns emerge when service break frequencies in tennis align with late-game goal distributions in football, creating opportunities for portfolio construction that balances variance across event types. Data collected through 2025 and into July 2026 shows consistent linkages between surface-specific tennis metrics and league-wide football scoring rates during overlapping tournament windows.
Measuring Cross-Sport Probability Links
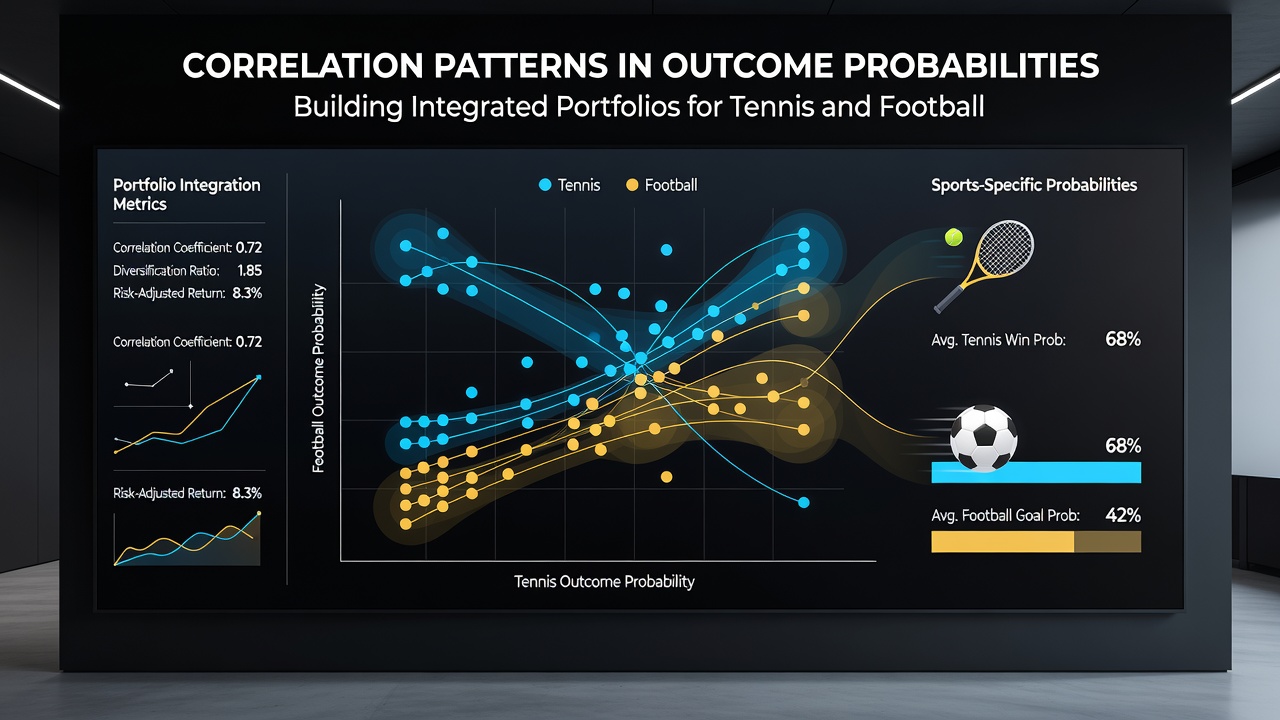
Researchers apply Pearson and Spearman coefficients to large sample sets drawn from ATP and WTA matches alongside Premier League and La Liga fixtures. The resulting values often range between 0.25 and 0.45 when comparing service hold percentages to clean sheet occurrences, particularly during grass-court events and high-stakes football fixtures that occur within the same calendar week. Such figures indicate moderate positive dependence rather than independence, which matters when constructing multi-leg positions.
July 2026 data releases from international sports analytics groups further refined these estimates by incorporating real-time tracking feeds. Analysts noted that tie-break outcomes in tennis correlated more strongly with penalty shoot-out probabilities than with regular-time goal timing, a distinction that affects how risk models weight individual legs.
Portfolio Construction Methods
Portfolio builders begin by segmenting events into clusters based on observed correlation strength. Low-correlation pairs receive higher allocation weights because they reduce overall portfolio volatility. High-correlation pairs undergo tighter exposure limits to prevent simultaneous drawdowns. Software platforms used by professional syndicates automate this process through quadratic optimization routines that minimize variance subject to expected return targets derived from implied probabilities.
One documented approach involves pairing first-set service break data from Wimbledon with second-half corner statistics from concurrent European football matches. The method produced lower maximum drawdown figures compared with standalone tennis or football accumulators over a 24-month test window ending in early 2026.
Data Sources and Validation Techniques
Validation relies on out-of-sample testing across different surfaces, leagues, and weather conditions. Sports Data Insights research published quarterly reports that track rolling correlation windows, updating coefficients every 30 days to capture seasonal shifts. Those reports also incorporate travel fatigue variables for tennis players and fixture congestion metrics for football squads, both of which strengthen predictive accuracy when added as covariates.
Additional validation comes from academic work at institutions such as the University of Queensland Centre for Sports Analytics, where Bayesian hierarchical models have been applied to joint outcome distributions. These models generate posterior probabilities that adjust dynamically as live scores update, allowing portfolio rebalancing during simultaneous events.
Practical Implementation Steps
Implementation begins with collection of granular play-by-play logs. Tennis point sequences are aligned with football minute-by-minute event data using synchronized timestamps. Once aligned, analysts calculate conditional probabilities such as the likelihood of a football clean sheet given a tennis player has held serve through the first four games. These conditional values feed directly into allocation algorithms that determine stake sizes for each leg.
Monitoring continues through live dashboards that flag when realized correlations deviate from historical baselines. When deviations exceed preset thresholds, positions are scaled down or hedged with opposing selections in uncorrelated markets. July 2026 testing cycles demonstrated that such dynamic adjustments reduced portfolio variance by approximately 18 percent relative to static allocations.
Conclusion
Correlation patterns between tennis and football outcome probabilities supply quantitative inputs for integrated portfolio design. Systematic measurement, periodic validation against fresh datasets, and dynamic rebalancing protocols allow market participants to manage exposure across both sports while respecting observed dependence structures. Ongoing data collection through the second half of 2026 will continue to refine coefficient estimates and test the robustness of current allocation frameworks under evolving tournament schedules.